TRG | The Bottom Line – 10/2
As TRG gathers feedback from the field on Q3’26 heavy materials (HM) trends, we have been struck by “have” and “have nots.” Broad end-market themes largely remain intact: 1) Resi remains very weak (with a few multi-family greenshoots), 2) non-res/commercial is dominated by mega projects, and 3) public remains (mostly) steady. Data centers, industrial megaprojects and select public work continue to see strong/steady demand in certain markets, while residential and “traditional” commercial construction remains tepid. Public remains steady with nuances by state in terms of letting trends as we head into the seasonal construction slowdown. A handful of states (notably CA & TX) noted fewer projects to bid in recent weeks. In general, there appear to be more bidders for projects today, with public projects attracting 7–8 bidders versus 4–5 historically. This is normal ahead of each highway bill reauthorization. Diesel, to state the obvious, will be a cost headwind in the quarter for companies, paving the way for more meaningful price increases in coming months to offset the crushing impact. Diesel costs are up ~40% since the end of Q2’26, and companies are feeling the squeeze.
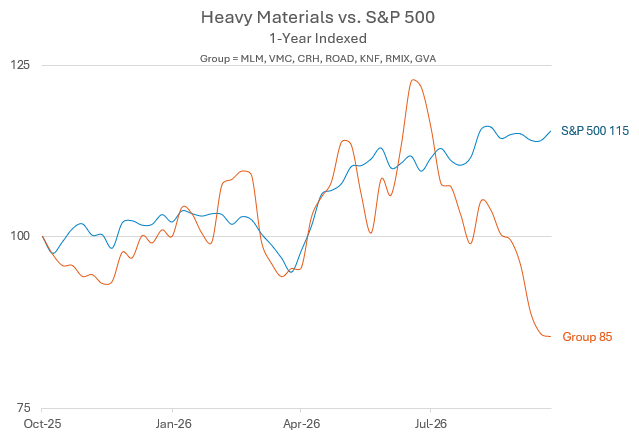
The S&P 500 is up 15% over the past twelve months, while heavy materials names are trading off 25%+ over the same time period. From a valuation standpoint, one could make the argument that current public company EV/EBITDA valuations are well below what you could buy a private HM company. Even after taking account various headwinds, this simply feels overdone.
Disclosure: This content reflects the independent views of Thompson Research Group, LLC (“TRG”), is provided for informational purposes only, and does not constitute an offer or solicitation to buy or sell any security. Additional information, including analyst certification and compensation-related conflicts of interest, may be found here: (disclosures).