TRG | The Bottom Line – 9/25
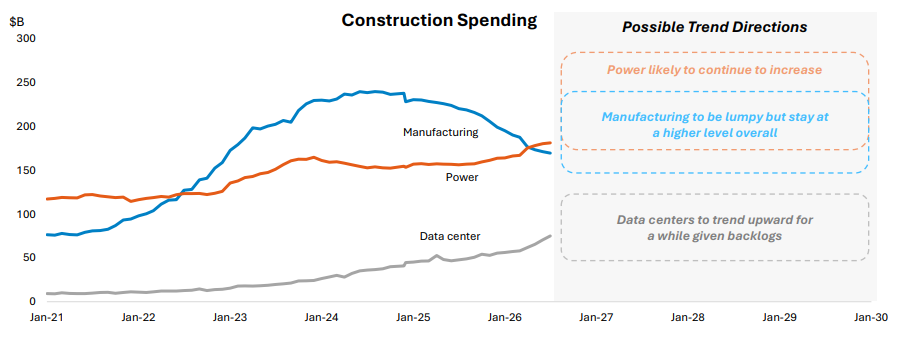
TRG this week published two thought pieces hitting on two hot topics: Housing & Reshoring. TRG’s “Housing Market Perspective: Locked Up For Now, Loaded for Later, But May Take Awhile to Unwind” report outlines how we continue to expect housing activity overall will be stuck in neutral and that effective demand could remain at these subdued levels for longer. While there are likely a myriad of distinct and overlapping reasons for this, we believe one key reason is the divergence of mortgage rates of existing homeowners. In particular, the imbalance of rates. It is estimated that ~60% of U.S. homeowners have a mortgage, and of this, ~70% of homes with a mortgage have a rate of 5% or less. This has been a slow-melting ice cube that has almost nowhere to go but down. With the current 30-year mortgage rate at nearly 7%, this means the majority of sellers who need to purchase a home will graduate to a higher-rate mortgage. TRG’s “Reshoring is Rotating, Not Ending: From a subsidy-driven first wave into a demand-driven second wave” noted that recent datapoints around the reindustrialization theme look contradictory in isolation. Manufacturing construction spend has been down for 2 years, the 2026 Reshoring Initiative survey has mixed results, and U.S. investments across the supply chain continue to be announced. Read together, they describe a reshoring trend rotating from a subsidy-driven first wave into a demand-driven second wave, not a trend that is ending.
Disclosure: This content reflects the independent views of Thompson Research Group, LLC (“TRG”), is provided for informational purposes only, and does not constitute an offer or solicitation to buy or sell any security. Additional information, including analyst certification and compensation-related conflicts of interest, may be found here: (disclosures).